$15,000 Mobile Home for Sale in Goldsboro, North Carolina – Affordable 2-Bedroom Manufactured Home in Tanglewood MHP
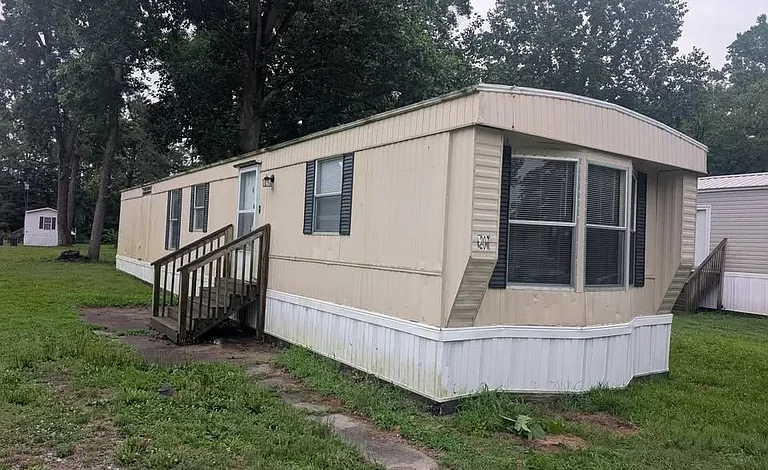
$15,000 Mobile Home for Sale in Goldsboro, North Carolina – Affordable 2-Bedroom Manufactured Home in Tanglewood MHP
Finding affordable housing in North Carolina can be challenging for buyers who want to own a residence without spending hundreds of thousands of dollars on a traditional single-family property. As housing costs, mortgage rates, insurance premiums, and everyday living expenses continue to influence household budgets, manufactured homes remain an option worth exploring.
One property that may interest budget-conscious buyers is located at 3201 Central Heights Rd #207, Goldsboro, NC 27534, where a two-bedroom manufactured home is advertised for $15,000.
The residence offers approximately 924 square feet of interior living space and includes two bedrooms and one full bathroom. It is located within Tanglewood Mobile Home Park, also identified as Tanglewood MHP, in the Goldsboro area of North Carolina.
The advertised home dimensions are approximately 14 feet by 66 feet, consistent with the reported 924-square-foot interior area.
At first glance, the relatively low asking price may appeal to individuals searching for an inexpensive home, an alternative to apartment living, or a smaller residential property.
However, one essential financial detail deserves immediate attention: the community charges $555 per month in lot rent.
The listing also displays a monthly HOA fee of $555. Because the advertised lot rent and HOA amount are identical, buyers should verify whether these represent the same charge rather than assuming they are two separate monthly fees.
Another important requirement is that every occupant aged 18 or older must complete an application and receive community approval before moving in.
This means that purchasing the manufactured home does not automatically guarantee the right to occupy its current location.
This comprehensive guide examines the property’s features, monthly expenses, manufactured-home financing options, insurance considerations, community approval requirements, and important questions buyers should ask before making a purchase.
Property Overview: 3201 Central Heights Rd #207, Goldsboro, NC 27534
The property is classified as a mobile or manufactured home.
It offers approximately 924 square feet of interior living area, with two bedrooms and one full bathroom.
The home is located in Tanglewood MHP, a manufactured housing community in Goldsboro, North Carolina.
Unlike a conventional house sold together with its land, this listing advertises monthly lot rent.
Prospective buyers should therefore distinguish between the price of the manufactured home and the continuing cost of occupying its space within the community.
Key Property Features
- Asking Price: $15,000
- Address: 3201 Central Heights Rd #207, Goldsboro, NC 27534
- Property Type: Mobile / Manufactured Home
- Bedrooms: 2
- Bathrooms: 1 full bathroom
- Interior Living Area: 924 square feet
- Reported Dimensions: 14 × 66 feet
- Community: Tanglewood MHP
- Monthly Lot Rent: $555
- Displayed Monthly HOA Fee: $555
- Price Per Square Foot: Approximately $16
- Community Approval: Required before occupancy
- Adult Occupant Applications: Required for all occupants aged 18 or older
- Year Built: Not provided
- Lot Size: Not provided
The listing does not include detailed information about the home’s construction year, heating and cooling systems, appliances, roof condition, or recent renovations.
Those details should be verified before purchasing.
Why This $15,000 Manufactured Home May Attract Buyers
The most noticeable feature of the property is its advertised purchase price.
At $15,000, the home may appeal to people who are searching for a relatively inexpensive way to purchase residential housing.
However, the true cost of living in a manufactured home community involves both the initial purchase price and recurring monthly expenses.
A Lower Initial Purchase Price
Traditional single-family homes often require substantial savings for a down payment, closing costs, and financing.
A manufactured home advertised at $15,000 may be accessible to buyers with different financial circumstances.
Nevertheless, the low price does not establish the home’s condition or guarantee that financing will be available.
Understanding the Price Per Square Foot
The listing reports approximately $16 per square foot.
Dividing the asking price of $15,000 by the reported 924-square-foot living area produces approximately $16.23 per square foot.
This calculation can help explain the advertised pricing.
However, comparing the figure directly with the price per square foot of a traditional house can be misleading.
Conventional home sales may include land ownership, while this property is advertised with ongoing lot rent.
The Importance of Total Housing Costs
A buyer who focuses only on the $15,000 asking price may underestimate future expenses.
Monthly lot rent, utilities, insurance, maintenance, and possible financing payments can influence the overall affordability of the home.
A responsible purchase decision should account for all these factors.
Living in Goldsboro, North Carolina
Goldsboro is located in Wayne County in eastern North Carolina.
The city serves as an important regional community with residential neighborhoods, businesses, healthcare services, and employment opportunities.
Goldsboro is also associated with Seymour Johnson Air Force Base, an important part of the area’s identity and economy.
However, the characteristics of the broader city do not automatically establish the value or suitability of any individual property.
Exploring the Local Housing Market
Goldsboro offers a variety of housing types, including conventional houses, apartments, and manufactured homes.
Buyers should compare the total monthly cost of this property with other available housing options in the area.
A lower purchase price may be attractive, but ongoing lot rent can significantly affect long-term expenses.
Access to Local Amenities
Prospective residents should research nearby grocery stores, medical facilities, schools, pharmacies, and employment centers.
Actual travel times should be checked using the property’s address and the buyer’s intended destinations.
Transportation and Daily Convenience
Buyers should consider whether they will need a personal vehicle for work, shopping, and other activities.
The listing does not provide detailed information about public transportation or assigned parking.
Community parking rules should be verified before purchasing.
Tanglewood MHP: Understanding Manufactured Home Community Living
The home is located in Tanglewood Mobile Home Park.
Manufactured housing communities typically have rules and procedures that differ from those associated with traditional homeownership.
These rules can affect occupancy, exterior maintenance, parking, pets, and other aspects of daily life.
The listing does not provide a complete copy of the community’s regulations.
Community Approval Is Required
The listing explicitly states that all occupants aged 18 or older must complete an application and receive approval before moving in.
This requirement is especially important.
A buyer may be financially prepared to purchase the home but still need to satisfy the community’s application criteria.
Application Requirements
Manufactured home communities may request information about prospective residents.
However, the exact application requirements for Tanglewood MHP are not provided in the listing.
Buyers should request written information about application procedures, fees, screening criteria, and approval timelines.
Why Approval Should Be Addressed Early
Prospective buyers should determine how the community approval process interacts with the purchase agreement.
It may be important to understand what happens if an applicant does not receive approval.
The buyer should not assume that ownership of the manufactured home automatically creates the right to live in the park.
Understanding the $555 Monthly Lot Rent
The listing advertises monthly lot rent of $555.
This amount is separate from the $15,000 purchase price.
At the reported rate, twelve months of lot rent would total $6,660.
First-Year Cost Example
Suppose a buyer purchases the home for $15,000 in cash.
If the monthly lot rent remains $555, the first twelve months would cost an additional $6,660.
The combined purchase price and one year of lot rent would therefore equal $21,660.
This calculation excludes insurance, utilities, maintenance, application fees, taxes, and other potential expenses.
It is a simplified example rather than a complete estimate of ownership costs.
Five-Year Lot Rent Calculation
At $555 per month, five years of lot rent would total $33,300.
Adding the $15,000 purchase price would produce a combined amount of $48,300.
This figure does not include other expenses and assumes that lot rent remains unchanged.
Ten-Year Lot Rent Calculation
If the monthly rent stayed at $555 for ten years, the total lot rent would be $66,600.
Combined with the purchase price, that would equal $81,600.
These calculations demonstrate why buyers should consider long-term costs when evaluating manufactured housing.
Is the $555 HOA Fee Separate From Lot Rent?
The listing displays a monthly HOA fee of $555 and separately describes lot rent as $555 per month.
Because the amounts match, they may represent the same recurring charge.
However, the supplied information does not explicitly confirm this.
Avoid Double-Counting Expenses
Buyers should ask the community to clarify whether the displayed HOA fee is simply the listing platform’s classification of the monthly lot rent.
They should also request a written breakdown of all mandatory recurring fees.
What Services Are Included?
The listing does not specify whether the $555 payment includes water, sewer, trash collection, landscaping, or other services.
These details can affect the household budget.
A written lease or fee schedule should explain which services are included and which are billed separately.
A 924-Square-Foot Home With Two Bedrooms
The manufactured home offers approximately 924 square feet of interior living area.
This size may appeal to people who prefer a smaller residence or want to avoid the maintenance associated with a much larger house.
The layout includes two bedrooms and one full bathroom.
Understanding the 14 × 66 Dimensions
The advertised dimensions are 14 feet by 66 feet.
Multiplying those measurements produces 924 square feet.
This matches the reported interior area.
However, the listing does not include a detailed floor plan.
Room sizes, hallway dimensions, and storage areas should be verified during a showing.
Potential Advantages of Compact Living
Smaller homes may require less furniture and can be easier to organize.
However, actual maintenance costs and energy consumption depend on the home’s condition, insulation, equipment, and household usage.
A compact layout does not automatically guarantee lower utility bills.
Two Bedrooms for Flexible Residential Use
The home includes two bedrooms.
A second bedroom can provide flexibility for different household needs.
Depending on the floor plan, the rooms may accommodate sleeping arrangements, guests, or a home office.
Primary Bedroom Considerations
The listing does not provide bedroom dimensions.
Buyers should measure the available space before purchasing large furniture.
Closet capacity, window condition, ventilation, and electrical outlets are also worth inspecting.
Second Bedroom Possibilities
A second bedroom may serve as a guest room, study, or another residential space.
However, buyers should verify the actual room layout and any community occupancy requirements.
Storage and Organization
The listing does not identify closets, built-in storage, or exterior storage structures.
Prospective buyers should evaluate whether the available storage meets their needs.
One Full Bathroom: Essential Features to Inspect
The home includes one full bathroom.
The listing does not describe the bathroom’s fixtures, age, or recent upgrades.
Plumbing Inspection
Buyers should inspect the sink, toilet, bathing area, and visible plumbing connections.
Water pressure, drainage, and signs of leakage should be evaluated.
Moisture and Ventilation
Bathrooms can develop moisture-related problems when ventilation is inadequate.
Buyers should inspect flooring, wall surfaces, and areas around plumbing fixtures.
Future Bathroom Maintenance
Even a relatively small bathroom can require costly repairs if water damage affects the subfloor or surrounding materials.
A professional inspection may help identify hidden issues.
Kitchen Features and Appliance Verification
The listing does not specify which kitchen appliances are included.
It also does not describe countertop materials, cabinetry, or kitchen renovations.
Buyers should avoid assuming that a refrigerator, stove, or other appliances are part of the sale.
Questions About the Kitchen
Before purchasing, buyers should verify the condition of cabinets, countertops, plumbing fixtures, and electrical outlets.
They should also determine which appliances, if any, will remain.
Budgeting for Appliances
If essential appliances are not included, the buyer may need to purchase them separately.
Those expenses should be added to the overall housing budget.
Kitchen Safety
Electrical and plumbing systems should be evaluated before extensive use or renovation.
The listing does not establish the age or condition of these systems.
Heating, Cooling, and Energy Efficiency
The supplied listing does not identify the home’s heating or cooling equipment.
This is an important information gap.
North Carolina experiences both warm summers and cooler winter periods, making indoor temperature control an important consideration.
Heating System Verification
Buyers should confirm whether a heating system is installed and operational.
A qualified professional can inspect the equipment and identify potential safety concerns.
Air Conditioning
The listing does not confirm the presence of central air conditioning or other cooling equipment.
Prospective residents should verify the available systems during a showing.
Insulation and Utility Expenses
Energy efficiency depends on insulation, air sealing, windows, equipment, and the condition of the home.
Buyers may wish to request available utility billing history.
Actual monthly utility expenses cannot be determined from the supplied information.
Roof, Exterior, and Structural Condition
The listing does not provide the home’s year of manufacture or detailed construction materials.
It also does not describe the roof’s age or condition.
These missing details should be addressed through inspection.
Roof Inspection
A roof inspection should look for deterioration, leaks, drainage issues, and previous repairs.
The cost of roof work can vary significantly depending on materials and condition.
Exterior Walls and Windows
Buyers should inspect siding, trim, doors, and windows.
Moisture intrusion and deteriorated seals can affect interior conditions and energy efficiency.
Flooring and Subfloor
Manufactured homes can experience flooring problems when moisture enters the structure.
Soft spots, uneven surfaces, or visible damage should be evaluated professionally.
Manufactured Home Financing in North Carolina
Financing a manufactured home can differ from financing a conventional house.
The available options depend on the home’s age, condition, legal classification, and whether the land is owned or rented.
Chattel Loans
Some lenders offer loans for manufactured homes classified as personal property.
These are commonly called chattel loans.
Eligibility, interest rates, loan amounts, and repayment terms vary.
Personal Loans
Some buyers may investigate personal loans for relatively inexpensive manufactured homes.
However, borrowing costs depend on lender policies and credit qualifications.
Conventional Mortgage Limitations
Traditional mortgage products may require the manufactured home to meet specific property and ownership standards.
A home located on rented land may not qualify for certain conventional mortgage programs.
Cash Purchase Considerations
Because the advertised purchase price is $15,000, some buyers may consider paying cash.
A cash purchase avoids loan interest but does not eliminate monthly lot rent or other expenses.
Manufactured Home Insurance in North Carolina
Insurance is an important part of manufactured home ownership.
Policies may cover the structure, personal belongings, liability, and other risks, depending on the insurer and selected coverage.
Factors Affecting Premiums
Insurance costs can depend on the home’s age, condition, location, replacement value, and coverage limits.
Because the listing does not provide a construction year, buyers should verify that information before requesting quotes.
Weather-Related Risks
North Carolina properties may face risks associated with severe storms and heavy rainfall.
The specific exposure of this home should be evaluated using its location and available insurance information.
Coverage for Rented-Land Homes
Buyers should explain to insurers that the home is located in a manufactured housing community with monthly lot rent.
The ownership arrangement may affect policy requirements.
Understanding the Total Monthly Housing Budget
The $555 monthly lot rent is only one part of the budget.
Other expenses may include utilities, insurance, maintenance, and financing.
Illustrative Monthly Budget
Consider the following hypothetical monthly expenses:
- Lot rent: $555
- Insurance: $65
- Electricity and other utilities: $175
- Maintenance savings: $75
Under these assumptions, the monthly total would be $870, excluding loan payments, taxes, application fees, and any additional community charges.
The insurance, utility, and maintenance amounts are examples only, not verified costs for this property.
Actual expenses may be higher or lower.
Why Budgeting Matters
A home with a low purchase price can still create a meaningful monthly financial obligation.
Buyers should compare the complete cost with other housing options available to them.
Could This Be an Option for First-Time Home Buyers?
Some first-time buyers consider manufactured homes because the initial purchase price may be lower than that of traditional houses.
This listing may attract people who want to explore ownership without taking on a large conventional mortgage.
However, manufactured home ownership on rented land has distinct financial characteristics.
Potential Benefits
A lower purchase price may reduce the amount of money needed for acquisition.
A smaller home may also suit buyers who do not require extensive living space.
Important Limitations
The buyer may not own the underlying land.
Monthly lot rent continues after the home has been paid for.
Community approval is required before occupancy.
These factors should be weighed against the potential advantages.
Manufactured Housing and Retirement Planning
Some people approaching retirement explore smaller homes as a way to manage housing expenses.
A two-bedroom manufactured home may be worth considering for certain household arrangements.
However, long-term affordability depends on recurring expenses and the condition of the home.
Fixed-Income Considerations
Buyers relying on a fixed income should investigate potential lot rent increases and other recurring charges.
Accessibility
The listing does not provide accessibility information.
Buyers should inspect entry steps, doorway widths, bathroom arrangements, and other features relevant to their needs.
Long-Term Maintenance
A manufactured home may require repairs over time.
Maintaining a reserve for unexpected expenses is important, particularly when household income is limited.
Can This Manufactured Home Be Used as a Rental Property?
Some investors purchase manufactured homes with the intention of renting them.
However, manufactured housing communities may restrict rental arrangements.
The listing does not establish whether subleasing is permitted.
Verify Community Rules
Before considering the property as an investment, buyers should request written confirmation of the park’s rental policies.
Rental Income Analysis
If renting is permitted, investors should compare potential rental income with lot rent, insurance, maintenance, vacancy, and other costs.
No verified rental income is supplied.
Therefore, profitability cannot be calculated from the asking price alone.
Community Application and Approval Requirements
One of the listing’s clearest requirements concerns adult occupants.
Every person aged 18 or older must submit an application and receive approval before moving in.
What Buyers Should Ask
Prospective residents should confirm the application fee, required documentation, approval criteria, and expected processing time.
They should also ask whether every adult occupant must apply separately.
Approval Before Closing
Buyers should understand how the application process relates to the purchase agreement.
They should avoid assuming that a completed home purchase automatically guarantees community acceptance.
Written Community Rules
A copy of the park’s rules can help buyers understand expectations concerning occupancy, parking, pets, guests, maintenance, and exterior changes.
Important Questions Before Purchasing
Before making an offer, prospective buyers should investigate the following:
- Is the asking price still $15,000?
- Is the monthly lot rent still $555?
- Is the displayed HOA fee the same charge as lot rent?
- Which utilities or services are included?
- Are additional monthly fees required?
- What are the community application requirements?
- What happens if an applicant is not approved?
- What year was the home manufactured?
- Is the ownership title clear?
- Are there unpaid lot fees or other liens?
- What is the condition of the roof?
- Are heating and cooling systems installed and working?
- Which appliances are included?
- Are there restrictions on pets or parking?
- Can the home remain on its current lot after the sale?
- Are there restrictions on resale or renting?
- What insurance coverage is required?
- Are there any known repairs that must be completed?
Answers to these questions can help buyers make more informed decisions.
Frequently Asked Questions About 3201 Central Heights Rd #207
What is the asking price?
The manufactured home is advertised for $15,000.
Where is the property located?
It is located at 3201 Central Heights Rd #207, Goldsboro, NC 27534, within Tanglewood MHP.
How many bedrooms and bathrooms does it have?
The home includes two bedrooms and one full bathroom.
How large is the home?
The reported interior living area is 924 square feet.
What are the home’s dimensions?
The listing describes the home as approximately 14 feet by 66 feet.
Is the land included in the purchase?
The listing advertises monthly lot rent of $555. Buyers should verify the ownership and lease terms rather than assuming the land is included.
Is the HOA fee separate from lot rent?
The listing displays a $555 monthly HOA fee and $555 monthly lot rent. Buyers should confirm whether these are the same charge.
Does the community require approval?
Yes. All occupants aged 18 or older must complete an application and receive approval before moving in.
What year was the home built?
The supplied listing does not provide a construction year.
Are appliances included?
The listing does not specify included appliances.
Can the home be financed?
Financing may be available through certain manufactured-home lenders, depending on eligibility and property requirements.
Is this home suitable for rental investment?
That depends on the community’s rules and the property’s financial characteristics. Rental permission is not established by the listing.
Final Thoughts: A $15,000 Manufactured Home With Important Community Requirements
The manufactured home at 3201 Central Heights Rd #207, Goldsboro, NC 27534, offers an advertised purchase price of $15,000 and approximately 924 square feet of interior living space.
Its two-bedroom, one-bathroom layout may appeal to buyers seeking a compact residence in North Carolina.
The property is located in Tanglewood MHP, where the advertised monthly lot rent is $555.
That ongoing expense is a major part of the financial decision.
Buyers should also clarify whether the displayed HOA fee represents the same monthly charge.
In addition, the community requires every adult occupant to complete an application and receive approval before moving in.
These requirements make it important to investigate both the home and the community before purchasing.
The listing does not provide detailed information about the home’s age, heating and cooling systems, appliances, or structural condition.
A professional inspection and review of the community lease can help buyers better understand the risks and responsibilities involved.
For buyers who are comfortable with manufactured-home ownership on rented land, this listing may be worth investigating.
Ultimately, the most important consideration is not simply the $15,000 asking price, but whether the home, monthly expenses, and community requirements fit the buyer’s long-term housing needs.
Final Property Summary
Property Address: 3201 Central Heights Rd #207, Goldsboro, NC 27534
Asking Price: $15,000
Property Type: Mobile / Manufactured Home
Bedrooms: 2
Bathrooms: 1 Full Bathroom
Interior Living Area: 924 Square Feet
Reported Home Dimensions: 14 × 66 Feet
Community: Tanglewood MHP
Monthly Lot Rent: $555
Displayed Monthly HOA Fee: $555 — verify whether this is the same charge as lot rent
Community Approval: Required
Adult Occupant Applications: Required for everyone aged 18 or older
Year Built: Not specified
Lot Size: Not specified
Disclaimer: This article is based on the supplied real estate listing and is intended for informational purposes only. Prices, availability, property condition, community fees, financing options, and occupancy requirements may change. Buyers should independently verify all information, confirm whether the HOA fee and lot rent represent the same payment, review community rules, obtain approval where required, and arrange appropriate inspections before purchasing.
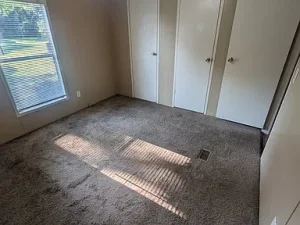
Listed on Zillow.