3 beds 3 baths 1,539 sqft
Est. $5,000 Foreclosure Auction in Pensacola, Florida – 3-Bedroom Home Built in 2017 With 2-Car Garage
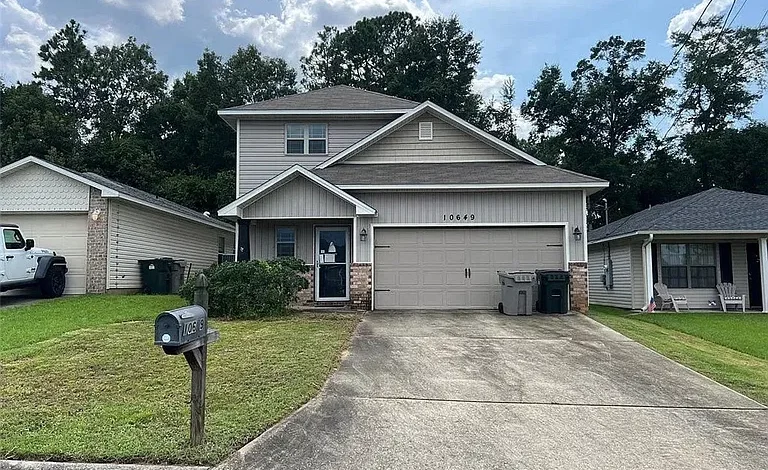
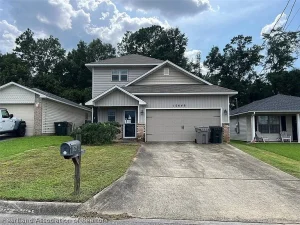
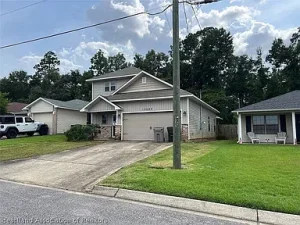
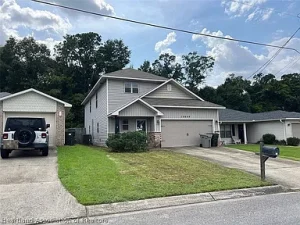
A foreclosure auction in Pensacola, Florida is attracting attention because of its extremely low opening bid and comparatively recent construction. Located at 10649 Senegal Dr, Pensacola, FL 32534, this single-family residence offers 3 bedrooms, 2.5 bathrooms, approximately 1,539 square feet of interior living space, a 2-car garage, and a 6,098-square-foot lot.
The property was built in 2017, making it much newer than many homes that appear in foreclosure or distressed-property listings. That alone makes it worth a closer look for investors, cash buyers, renovators, and experienced auction participants.
The most important detail, however, is the auction structure. The listing shows an estimated figure of $5,000, but this should not be interpreted as a traditional asking price or as the expected final purchase price. According to the listing, the figure represents the opening bid for an online foreclosure auction, with the auction scheduled to end on October 15, 2026 at 12:00 PM EST.
The home is being sold as is, and the listing identifies cash as the purchase term. Buyers should therefore approach the property differently from a normal retail home purchase. Inspection access, title conditions, liens, occupancy, financing, property condition, buyer premiums, deposit requirements, and closing deadlines should all be investigated carefully before bidding.
For the right buyer, however, the combination of a newer 2017 home, three bedrooms, multiple bathrooms, garage parking, no reported HOA, and a low opening bid could make this an especially interesting foreclosure opportunity.
Property Overview
Important details reported for the property include:
- Opening auction bid: Est. $5,000
- 3 bedrooms
- 2 full bathrooms
- 1 half bathroom
- 3 bathrooms total
- Approximately 1,539 square feet of interior living area
- Approximately 2,035 square feet of total structure area
- Built in 2017
- Single-family residence
- One-story layout
- 2-car garage
- Approximately 6,098-square-foot lot
- Front porch
- No private pool
- No HOA reported
- Annual reported property taxes of approximately $3,200
- Tax-assessed value approximately $226,874
- Zestimate listed at approximately $157,400
- Sold as is
- Cash terms
- Foreclosure auction
- Auction end scheduled for October 15, 2026 at 12:00 PM EST
- MDR zoning description
- Pensacola location
For a distressed property, the home has several characteristics that could appeal to both investors and owner-occupants, assuming the auction terms and property condition are acceptable.
Understanding the $5,000 Opening Bid
The $5,000 figure is not the same thing as a $5,000 purchase price.
This distinction is essential.
In an online foreclosure auction, the listing may begin at a very low number to attract bidders. The final price can increase substantially depending on competition.
A property with a low opening bid may ultimately sell for tens of thousands—or much more—above that figure.
Prospective buyers should therefore avoid calculating investment returns based on the assumption that the home will actually be acquired for $5,000.
The correct approach is to determine a maximum bid based on:
- Property condition
- Estimated repairs
- Comparable sales
- Taxes
- Auction fees
- Closing costs
- Potential liens
- Insurance
- Holding costs
- Expected resale or rental value
A disciplined bidder decides on that number before the auction becomes competitive.
Foreclosure Auction Ending October 15, 2026
According to the listing, the online foreclosure auction is scheduled to end on October 15, 2026 at 12:00 PM EST.
Anyone researching the property before that date should review the official auction platform for current bidding activity and complete terms.
Anyone reviewing the property after that date should verify whether:
- The auction concluded
- The reserve or sale requirements were met
- The property was sold
- The property was relisted
- The winning bid was confirmed
Auction status can change quickly, so current information should always be confirmed directly.
Sold As-Is
The home is offered as is.
That means the seller is generally not promising to make repairs before closing.
For foreclosure properties, “as is” can involve more uncertainty than in a conventional sale.
The buyer may be responsible for discovering issues involving:
- Roof
- Plumbing
- Electrical
- HVAC
- Water damage
- Mold
- Appliances
- Flooring
- Windows
- Garage
- Landscaping
- Utilities
The seller may have limited knowledge about the current condition.
A buyer should therefore budget conservatively.
Built in 2017
One of the biggest reasons this foreclosure stands out is the 2017 construction date.
A 2017 home is relatively new compared with many distressed properties.
Newer construction can sometimes mean fewer concerns involving:
- Old electrical wiring
- Galvanized plumbing
- Lead-based paint
- Very old roofing
- Outdated floor plans
However, newer does not mean problem-free.
Foreclosed homes may suffer from:
- Deferred maintenance
- Storm damage
- Water leaks
- Vandalism
- Utility shutoffs
- Improper repairs
- Occupancy-related damage
The home’s age is an advantage, but inspection remains essential.
Three Bedrooms
The property contains 3 bedrooms.
A three-bedroom layout is widely appealing.
It can work for:
- Families
- Couples
- Owner-occupants
- Renters
- Home offices
- Guest rooms
For investors, three-bedroom homes often appeal to a broader rental market than one-bedroom or two-bedroom properties.
If the home is in good condition, the bedroom count could support both resale and rental strategies.
Two Full Bathrooms and One Half Bathroom
The home includes:
- 2 full bathrooms
- 1 half bathroom
That is a strong configuration for a 1,539-square-foot home.
The half bathroom can be useful for guests, while the two full bathrooms support household convenience.
For families, multiple bathrooms can reduce congestion during busy mornings.
For resale, 2.5 bathrooms often make a home more competitive than similarly sized properties with only one or two baths.
Approximately 1,539 Square Feet
The interior living area is reported at approximately 1,539 square feet.
This is a practical size for a modern three-bedroom home.
It is large enough to provide comfortable living space without the higher maintenance costs associated with very large houses.
Potential room uses may include:
- Primary bedroom
- Two secondary bedrooms
- Living room
- Kitchen
- Dining area
- Bathrooms
- Laundry
- Storage
The exact floor plan should be reviewed through available auction documents or virtual tours.
Approximately 2,035 Square Feet of Total Structure Area
The listing reports approximately 2,035 square feet of total structure area.
The difference between total structure area and livable area may include:
- Garage
- Porch
- Other non-conditioned spaces
This distinction matters when comparing the property with other homes.
Buyers should always compare finished living area with finished living area rather than using total structure area alone.
One-Story Layout
The house is described as a one-story residence.
Single-level living has several advantages.
It can appeal to:
- Families with young children
- Retirees
- Buyers with mobility concerns
- People who prefer simpler layouts
There are no stairs between bedrooms and main living areas.
This can improve convenience and future resale appeal.
Two-Car Garage
The property includes a 2-car garage.
The garage dimensions are approximately 20 feet by 19 feet.
A two-car garage can add significant value.
Potential uses include:
- Vehicle parking
- Storage
- Workshop
- Lawn equipment
- Bicycles
- Seasonal items
In Florida, garage space can also protect vehicles from sun, rain, and storms.
Front Porch
The home includes an open front porch.
A front porch can improve curb appeal and create a small outdoor sitting area.
Potential improvements could include:
- Seating
- Lighting
- Planters
- Exterior paint
- Entry upgrades
For a foreclosure property, simple exterior work can sometimes produce a noticeable visual improvement.
6,098-Square-Foot Lot
The property sits on approximately 6,098 square feet of land.
That is roughly 0.14 acre.
This is a typical suburban-style lot size.
It may provide enough room for:
- Front yard
- Backyard
- Patio
- Small garden
- Outdoor seating
The lot is not large, but it may be easier to maintain than a larger property.
No HOA Reported
The listing reports no HOA.
That can be attractive to buyers who want to avoid:
- Monthly HOA dues
- Annual association fees
- Architectural restrictions
- Community approval processes
However, city, county, deed, and zoning rules still apply.
No HOA does not mean unrestricted use.
Pensacola Location
Pensacola is one of the better-known cities in Florida’s Panhandle.
The broader area attracts residents because of:
- Gulf Coast access
- Employment
- Military presence
- Beaches
- Shopping
- Healthcare
- Schools
- Outdoor recreation
Location can significantly affect both rental demand and resale value.
Buyers should evaluate the specific neighborhood rather than relying only on the Pensacola name.
MDR Zoning
The zoning description is listed as MDR.
Buyers should confirm exactly what MDR means under the applicable local zoning code.
It may relate to a medium-density residential classification.
Zoning can influence:
- Residential use
- Rental use
- Accessory structures
- Parking
- Additions
- Future redevelopment
For a standard single-family residence, the existing use may already comply, but verification is still worthwhile.
Zestimate of Approximately $157,400
The listing includes a Zestimate of approximately $157,400.
Automated home-value estimates can provide a rough reference, but they should not be used as the sole basis for bidding.
A foreclosure property’s actual value may be lower or higher depending on:
- Interior condition
- Repair needs
- Occupancy
- Roof
- HVAC
- Water damage
- Comparable sales
An investor should rely primarily on recent comparable sales and a realistic repair estimate.
Tax-Assessed Value of Approximately $226,874
The property’s reported tax-assessed value is approximately $226,874.
This figure is notably higher than the listed Zestimate.
That difference highlights why no single automated number should be treated as definitive.
Tax assessment values are created for property-tax purposes.
Market value is determined by buyer demand and condition.
Auction value depends on bidder competition and property risk.
These can all be very different numbers.
Annual Property Taxes of Approximately $3,200
The annual property tax is reported at approximately $3,200.
Buyers should include this in both rental and resale calculations.
For investors, taxes affect:
- Monthly holding cost
- Rental cash flow
- Long-term return
Prospective buyers should also verify whether any delinquent taxes exist and whether the auction terms specify how they are handled.
Cash-Only Terms
The listing identifies cash as the purchase term.
That is common in foreclosure auctions.
Cash requirements can create barriers for ordinary buyers because traditional financing may not fit tight auction timelines.
A bidder may need:
- Proof of funds
- Deposit
- Immediate contract execution
- Fast closing
Even buyers planning to use financing later may need sufficient cash to complete the initial transaction.
Why Foreclosure Auctions Often Require Cash
Auction sellers usually want certainty.
Traditional mortgages can be delayed by:
- Appraisals
- Repairs
- Underwriting
- Inspections
- Loan conditions
Cash eliminates much of that uncertainty.
However, it also transfers more risk to the buyer.
The bidder needs to be confident in the property before committing funds.
No Heating Listed
One unusual fact is that the listing states Heating: None.
For a 2017 house in Florida, this could mean:
- The system is missing
- The HVAC is nonfunctional
- Data is incomplete
- Auction records are inaccurate
This point should be investigated carefully.
A modern Florida home would typically have some form of HVAC.
If the system has been removed or damaged, replacement could be a major expense.
No Cooling Listed
The listing also states Cooling: None.
This is particularly important in Pensacola.
Air conditioning is effectively essential in Florida.
A missing or failed HVAC system can cost thousands of dollars to replace.
Buyers should not assume the home has working central air simply because it was built in 2017.
The system should be physically inspected if access is available.
HVAC Could Be a Major Repair Item
If both heating and cooling equipment are absent or damaged, a buyer may need:
- Air handler
- Outdoor condenser
- Thermostat
- Duct inspection
- Electrical work
- Refrigerant lines
The total cost could materially affect the maximum bid.
This is exactly the type of issue auction buyers need to price in before bidding.
Utilities Listed as “Other”
Electric, sewer, and water information is not clearly specified.
The listing uses terms such as:
- Other
- See Remarks
That means buyers should verify utility status directly.
Important questions include:
- Is electricity active?
- Is water connected?
- Is the home on public sewer?
- Are there unpaid utility balances?
- Has service been disconnected?
- Are meters present?
Utility uncertainty is common in foreclosure listings.
Roof Listed as “Other”
The roof type is also described only as Other.
Because the home was built in 2017, the roof may still have useful life, but Florida weather can accelerate wear.
Pensacola is exposed to:
- Heavy rain
- Wind
- Tropical storms
- Hurricanes
- Intense sun
A roof inspection is essential.
Florida Storm Risk
Location in Florida means buyers should think carefully about storm exposure.
Potential issues include:
- Wind damage
- Roof damage
- Water intrusion
- Flooding
- Insurance availability
A foreclosure may have damage that was never fully repaired after a storm.
This should be part of the inspection process.
Insurance Can Be a Major Cost
Florida homeowners insurance has become an important ownership expense.
Before bidding, buyers should obtain realistic insurance estimates.
Insurers may evaluate:
- Roof age
- Wind mitigation
- Electrical system
- Plumbing
- HVAC
- Storm shutters
- Flood zone
If major systems are missing or damaged, insurance may be difficult to obtain until repairs are completed.
Flood-Zone Research
The listing does not provide flood-zone information.
Buyers should check official flood maps.
Pensacola properties can vary significantly in flood exposure.
Flood status may affect:
- Insurance
- Financing
- Resale
- Renovation rules
A property that appears inexpensive can become costly if flood-insurance premiums are high.
As-Is Foreclosure Risk
Foreclosure buyers must accept more uncertainty than retail buyers.
Potential hidden issues include:
- Unpaid liens
- Damaged appliances
- Missing fixtures
- Deferred maintenance
- Mold
- Plumbing leaks
- HVAC theft
- Broken windows
- Trash or debris
- Occupancy problems
The lower purchase price needs to compensate for these risks.
Due Diligence Before Bidding
A serious buyer should investigate:
- Title
- Liens
- Taxes
- Occupancy
- HOA status
- Utility status
- Roof
- HVAC
- Electrical
- Plumbing
- Windows
- Garage
- Structural condition
- Flood zone
- Insurance
- Auction premium
- Closing deadline
Missing even one major issue could materially change the economics.
Buyer Premium
Many auction platforms charge a buyer premium.
This is an additional fee added to the winning bid.
For example, if the winning bid is $100,000 and the buyer premium is 5%, the buyer may owe an additional $5,000.
Buyers should confirm whether a premium applies before bidding.
Earnest Money or Deposit
Online auctions often require:
- Registration
- Credit-card authorization
- Earnest-money deposit
- Proof of funds
Failure to complete the purchase after winning can create serious financial consequences.
Auction terms should be read carefully before placing a bid.
Closing Deadlines
Foreclosure auctions often require faster closings than standard home sales.
A buyer may have only days or a few weeks to close.
This makes preparation important.
Cash should be available.
Title review should be ready.
Insurance should be researched in advance.
Potential Owner-Occupant Opportunity
If the home is in reasonable condition, it could appeal to a cash buyer seeking a primary residence.
A 2017 three-bedroom home with 2.5 bathrooms and a garage provides many features typical of a conventional family home.
The challenge is auction uncertainty.
Owner-occupants may be less comfortable than investors with limited inspections or as-is conditions.
Potential Rental Property
The home may also work as a rental investment.
Three-bedroom homes can attract:
- Families
- Military households
- Professionals
- Long-term tenants
Rental feasibility depends on neighborhood demand and local rental rates.
An investor should research comparable rents before bidding.
Potential Fix-and-Flip
A newer home can also appeal to flippers because the structural layout may already be modern.
If repairs are mainly:
- Paint
- Flooring
- HVAC
- Appliances
- Landscaping
the project may be more straightforward than renovating a century-old house.
However, foreclosure damage can be unpredictable.
Repair Budget Should Include Contingency
Investors often make the mistake of estimating only visible repairs.
A safer approach is to include a contingency.
For example:
Visible repairs + 10% to 20% contingency
This can help cover surprises discovered after closing.
Comparable Sales Matter More Than Zestimate
The correct bidding strategy should be based on recent comparable sales of similar homes.
Good comparables should match:
- Same neighborhood or nearby area
- Similar square footage
- Similar age
- Similar bedroom count
- Similar lot size
- Similar garage arrangement
An investor can then estimate a realistic after-repair value.
Example Investment Formula
A simple auction investment framework might be:
Expected resale value
minus repairs
minus closing costs
minus holding costs
minus selling costs
minus desired profit
equals maximum bid
This helps prevent emotional bidding.
Why the 2017 Build Date Matters for Resale
A home built in 2017 may appeal to buyers who prefer modern construction.
Potential advantages can include:
- More current floor plan
- Modern electrical standards
- Newer plumbing
- Newer insulation
- More efficient windows
Again, these advantages depend on current condition.
No Pool
The home does not have a private pool.
Some Florida buyers may view that as a disadvantage.
Others may appreciate avoiding:
- Pool maintenance
- Insurance costs
- Repairs
- Safety concerns
For a rental property, no pool can simplify maintenance.
Garage Adds Rental and Resale Appeal
A two-car garage can improve both rental demand and resale appeal.
Tenants and homeowners value garage space for:
- Vehicles
- Storage
- Tools
- Bicycles
In hot Florida weather, covered parking is especially useful.
Single-Level Living
The one-story layout may appeal to a wide range of buyers.
There are no stairs between living areas.
This can be useful for:
- Retirees
- Families with children
- Buyers with mobility limitations
That broadens the potential resale audience.
Front Porch Curb Appeal
A front porch can be improved inexpensively through:
- Paint
- Lighting
- Door hardware
- Planters
- Seating
Simple curb-appeal upgrades can help resale presentation.
Landscaping Potential
Foreclosures sometimes have neglected yards.
Basic improvements such as:
- Mowing
- Trimming
- Pressure washing
- Mulch
- Simple plants
can materially improve first impressions.
For investors, exterior cleanup can offer a high visual return relative to cost.
Three Days on Zillow
The property had been listed for only a few days according to the provided information.
That means the auction listing was relatively fresh and may still have been building interest.
The low opening bid could attract a significant number of watchers and bidders as the deadline approaches.
Online Views and Saves
The property had already generated more than 100 views.
That is not unusual for an auction listing with a $5,000 opening bid.
Many viewers may simply be curious.
However, serious bidder competition can increase rapidly near the auction close.
Tax Assessed Value Versus Opening Bid
The gap between the $226,874 assessed value and the $5,000 opening bid is dramatic.
That does not mean the buyer will instantly gain more than $200,000 in equity.
Auction opening bids are marketing and bidding mechanisms.
The final bid is what matters.
Auction Psychology
Low opening bids can create emotional bidding.
A buyer may start thinking:
“If I can get it for $50,000, that is still cheap.”
Then another bidder pushes it to $55,000.
Then $60,000.
Without a preplanned limit, bidders can easily exceed their financial model.
The best strategy is to determine the maximum acceptable bid before participating.
Title Work Is Essential
Foreclosure transactions may involve title complications.
Buyers should determine whether the sale provides:
- Clear title
- Special warranty deed
- Quitclaim deed
- Other transfer method
They should also understand which liens survive the sale.
A title professional or real estate attorney can help.
Occupancy Status
The listing does not clearly state whether the home is vacant.
This is critical.
If occupants remain in the property, the buyer may need to handle:
- Eviction
- Possession process
- Legal notices
Occupancy should be confirmed before bidding.
Appliances and Fixtures
The listing does not provide a detailed appliance package.
In foreclosures, appliances may be:
- Missing
- Damaged
- Nonfunctional
Buyers should not assume any appliance remains unless the auction terms specifically guarantee it.
Cosmetic Renovation Potential
If the house is structurally sound, cosmetic improvements could include:
- Paint
- Flooring
- Lighting
- Cabinet hardware
- Landscaping
- Fixtures
A newer home can sometimes respond well to simple updates.
Major Repair Risks
Potential expensive repairs include:
- HVAC replacement
- Roof replacement
- Water damage
- Mold remediation
- Electrical repair
- Plumbing leaks
Any one of these could significantly increase total project cost.
No HOA Could Help Investors
The absence of an HOA may simplify rental or resale plans.
There are no reported association approval processes or monthly dues.
However, local zoning and municipal rules still apply.
Rental Restrictions Should Still Be Checked
No HOA does not automatically mean unlimited rental freedom.
Buyers should verify:
- Local rental licensing
- Short-term rental rules
- Occupancy regulations
- Property-maintenance requirements
For long-term rentals, local landlord regulations should also be reviewed.
Potential Military Rental Demand
Pensacola has a strong military presence.
That can support rental demand in many parts of the metro area.
However, investors should study the exact neighborhood and commute times to relevant employers and bases rather than assuming demand.
School District Considerations
Families often evaluate schools when choosing a home.
Investors focused on resale or rental should research:
- Assigned schools
- District reputation
- Commute distance
School quality can influence demand even when the property itself is attractive.
Commuting and Shopping
Buyers should evaluate:
- Major roads
- Grocery stores
- Healthcare
- Shopping
- Employment centers
A well-located property may have stronger resale potential than a similar home in a less convenient area.
Inspection Challenges at Auction
Some foreclosure auctions provide limited interior access.
If no physical inspection is available, buyers must price in additional uncertainty.
Virtual tours can help, but they cannot replace:
- Roof inspection
- Plumbing tests
- HVAC testing
- Moisture detection
Limited inspection rights should reduce the amount a prudent bidder is willing to pay.
Investor Exit Strategies
Potential strategies include:
- Renovate and resell
- Renovate and rent
- Owner occupy
- Hold long term
Each strategy has a different maximum purchase price.
A flipper needs a profit margin.
A landlord focuses on rental yield.
An owner-occupant may accept a smaller financial margin because the property also provides housing value.
Cash Purchase Advantages
Cash buyers can move quickly.
They can avoid:
- Loan appraisal
- Mortgage underwriting
- Lender repair requirements
This can be particularly useful at auction.
The tradeoff is greater capital exposure.
Future Resale After Renovation
If properly renovated, a 2017 three-bedroom home with 2.5 bathrooms and a garage may compete well in the traditional retail market.
Good resale presentation could include:
- Functional HVAC
- Clean roof
- Fresh paint
- Durable flooring
- Updated fixtures
- Clean landscaping
- Working appliances
The final renovation level should match the neighborhood.
Avoid Over-Improving
An investor should not install luxury finishes if comparable homes do not support the cost.
The goal is to meet or slightly exceed neighborhood expectations, not create the most expensive home in the area.
Questions Buyers Should Ask Before Bidding
Prospective bidders should confirm:
- Is the home vacant?
- Is interior access available?
- Does a buyer premium apply?
- What deposit is required?
- What is the closing deadline?
- Are there outstanding liens?
- Are taxes current?
- What type of deed transfers?
- Is HVAC present?
- Is the roof damaged?
- Are utilities active?
- Is the property in a flood zone?
- Are there unresolved code violations?
- Does insurance appear available?
- What appliances remain?
These questions can materially affect the maximum bid.
Who Might Find This Property Attractive?
The property may appeal to:
- Cash investors
- Fix-and-flip buyers
- Landlords
- Experienced foreclosure buyers
- Owner-occupants with cash
- Contractors
The newer construction date is likely to be especially attractive.
Who Should Think Carefully Before Participating?
The auction may be unsuitable for:
- Buyers who need a conventional mortgage
- Buyers with no repair reserve
- First-time auction participants who do not understand the terms
- Buyers unwilling to accept as-is risk
- Buyers who need guaranteed move-in condition
Foreclosure auctions reward preparation.
Final Thoughts on 10649 Senegal Dr
At first glance, Est. $5,000 for a 3-bedroom, 2.5-bath home built in 2017 in Pensacola, Florida sounds almost unbelievable.
That is exactly why understanding the auction structure matters.
The $5,000 figure is the opening bid, not a guaranteed purchase price.
The final selling price will depend on bidding activity and the official foreclosure-auction terms.
The property offers approximately 1,539 square feet of interior living area, a 2-car garage, a 6,098-square-foot lot, a one-story layout, a front porch, and no reported HOA.
Its 2017 construction date distinguishes it from many distressed properties, which are often much older.
At the same time, buyers should take the listing’s uncertainties seriously.
Heating and cooling are both shown as “None,” while electrical, water, sewer, and roof information are incomplete or listed as “Other.” These gaps should not be ignored.
If the HVAC system is missing, the roof is damaged, utilities are disconnected, or the interior has suffered significant foreclosure-related deterioration, repair costs could quickly become substantial.
The property is being sold as is and listed for cash, meaning buyers should be prepared to make decisions with limited seller guarantees.
A careful bidder should research comparable values, determine realistic repair costs, verify title and lien status, investigate flood and insurance issues, review all auction fees, and establish a firm maximum bid before participating.
For an experienced investor, landlord, contractor, or cash buyer, this property may offer a compelling opportunity because it combines a low opening bid with relatively modern construction.
For an inexperienced buyer, the low number should not create false confidence.
The real opportunity is not simply the chance to buy a house beginning at $5,000. It is the possibility of acquiring a newer Pensacola home at a price that still makes financial sense after repairs, auction costs, taxes, insurance, and all other expenses are included.
Listed on Zillow